Analyst Highlights:
- Cash generation and borrowing now coexist: Microsoft reported positive quarterly free cash flow while pricing $25 billion of debt.
- Resilient growth and persistent inflation favor caution: the Fed’s pause leaves further tightening possible, rather than establishing an easing cycle.
- Inflation constrained households: real disposable income fell 0.3% in September, while higher nominal spending delivered almost no real consumption growth.
- Nvidia’s reported credit-guarantee discussions show how chip suppliers’ exposure can extend into customers’ infrastructure financing.
- IPO execution deserves scrutiny: pricing announcements, completed trading debuts and actual capital raised must be distinguished, particularly in OPay’s case.
- Bitcoin ETF demand weakened late: Friday’s $643.2 million withdrawal more than erased the preceding four sessions’ combined inflows.
IPOs in the week:
- Anthropic (proposed NASDAQ: ANT) — Filed its S-1 on October 26 for a proposed IPO; the filing did not specify the share count, price range or final offering size.
- Bambusa Therapeutics (NASDAQ: BBTX) — Priced approximately 10.56 million shares at $16, an upsized $168.9 million offering; shares closed Friday at $14.99, 6.31% below the offer price.
- Aspen Neuroscience (NASDAQ: ASPE) — Priced 9.375 million shares at $15, a $140.6 million offering; shares closed Friday at $14.89, 0.73% below the offer price.
- OPay (proposed NYSE: OPAY) — Announced 16 million ADSs at $19, implying $304 million in gross proceeds; shares did not begin trading Friday, leaving execution unresolved.
- Georgia Banking Company (NASDAQ: GBC) — Completed its direct listing without raising IPO capital; Friday’s $38.38 close was 27.9% above its last private-round price.
- BHAV Acquisition II (BHAIU) and SPACCircle Acquisition (SCQCU) — Each priced a $100 million SPAC offering, targeting technology-related acquisition opportunities.
Markets Weekly:
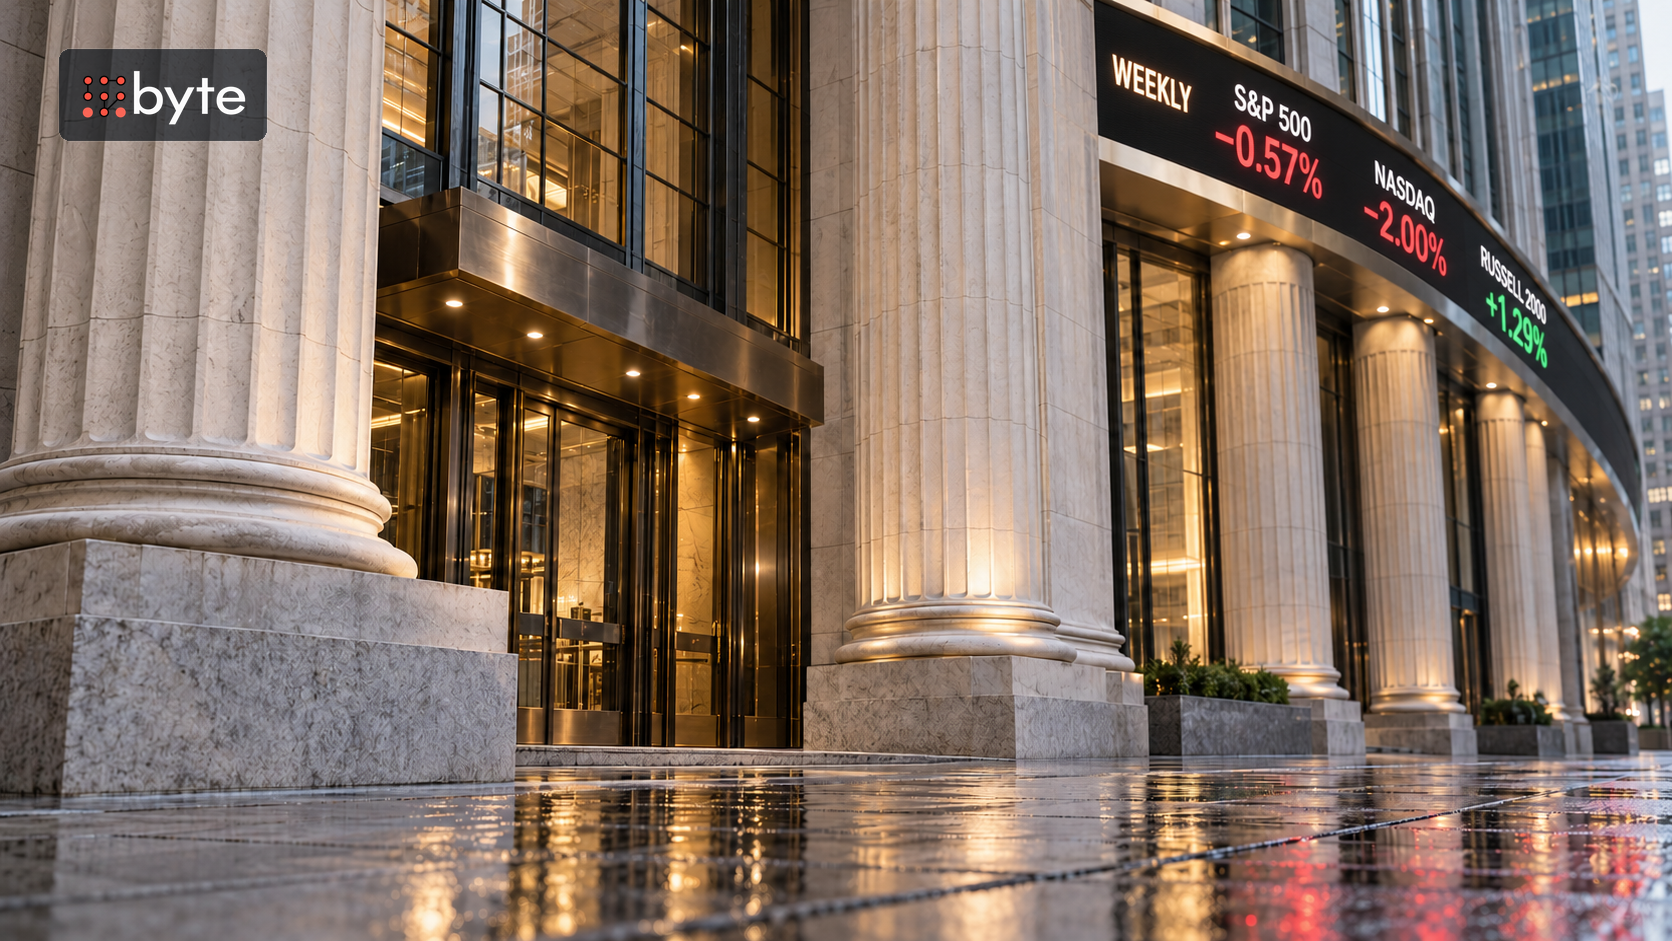
- S&P 500 closed at 7,580.07, falling 43.61 points, or 0.57% for the week.
- Russell 1000 closed at 4,124.50, falling 22.43 points, or 0.54% for the week.
- Russell 2000 closed at 2,811.84, rising 35.94 points, or 1.29% for the week.
- Russell 3000 closed at 4,297.04, falling 20.23 points, or 0.47% for the week.
- CBOE Volatility Index (VIX) closed at 19.42, falling 0.03 points, or 0.15% for the week.
- Dow Jones closed at 51,770.31, falling 444.85 points, or 0.85% for the week.
- NASDAQ Composite closed at 25,437.00, falling 518.34 points, or 2.00% for the week.
- Bitcoin closed at $78,248.45, falling $1,775.55, or 2.22% for the week.
- Ethereum closed at $2,273.05, falling $53.87, or 2.31% for the week.
- Solana closed at $94.45, falling $6.77, or 6.69% for the week.
- XRP closed at $1.2499, falling $0.0445, or 3.44% for the week.
- Gold closed at $3,898.90, falling $109.00, or 2.72% for the week.
- Silver closed at $49.276, falling $4.673, or 8.66% for the week.
- WTI closed at $104.12, rising $0.85, or 0.82% for the week.
- Brent closed at $117.64, rising $0.92, or 0.79% for the week.
- The Federal Reserve held rates at 3.75%–4.00% in a 10–2 vote; both dissenters favored a quarter-point increase.
- U.S. third-quarter GDP grew 3.4% annualized, accelerating from 2.2%, as investment and consumer spending supported the expansion.
- September PCE inflation reached 3.6% year over year, with core at 3.1%; inflation-adjusted consumer spending was nearly unchanged.
- Intel fell almost 29% Friday after disappointing guidance, exposing pressure from weaker PC demand and rising memory costs.
- Canada raised rates to 2.50%, while the ECB and Bank of Japan held steady amid persistent inflation risks.
- Microsoft priced $25 billion of senior unsecured notes for general corporate purposes, including potential capital spending; closing is expected November 4.
- Seven OPEC+ members kept December production targets unchanged; their next meeting is scheduled for November 29.
- U.S. spot Bitcoin ETFs recorded $202.4 million in weekly net outflows after Friday’s $643.2 million withdrawal.
Politics Weekly:
- Iran and Qatari mediators continued Doha talks on Sunday; a proposed Hormuz reopening timetable remained conditional on an agreement.
- Iran’s Revolutionary Guards said two tankers struck mines in Hormuz on Sunday; the account came through Iranian state media.
- Israel’s final election results gave Netanyahu’s bloc 53 of 120 seats, leaving coalition formation unresolved and Arab parties potentially pivotal.
- The Houthis claimed a missile strike on Saudi Arabia’s Ras Tanura refinery; Saudi authorities did not immediately confirm the attack.
- Britain’s budget paired household energy support and frozen fuel duty with higher taxes on banks, gambling, savers and landlords.
- China’s Communist Party expelled 33 senior officials at its plenum and scheduled the next Party Congress for late 2027.
- The Kremlin said talks were underway to lift U.S. sanctions on Russia’s sovereign investment fund; no agreement was announced.
Technology Advancements in the week:
- Nvidia was reportedly in talks to provide billions in credit guarantees for Nscale’s Anthropic data-center project; no agreement was announced.
- Oracle announced Google TPUs on OCI from 2027, making it the first hyperscaler outside Google to offer the chips.
- Microsoft reported $45.2 billion in quarterly capital expenditure and $18.6 billion in free cash flow, demonstrating capacity to fund AI expansion.
- Amazon reaffirmed approximately $220 billion in 2026 cash capital expenditure; trailing-year free cash flow was negative $42.4 billion.
- Google Cloud revenue rose 103% to $30.7 billion, with AI infrastructure, enterprise applications and TPU systems supporting growth.
- OpenAI began rolling out GPT-6.1 Terra across its API, ChatGPT Work and Codex for visual reasoning, computer use and writing.
- OpenAI and ServiceNow expanded their partnership across enterprise workflows, application development and cybersecurity, with several capabilities scheduled for 2027.
- Anthropic detailed six drug-development partnerships and its acquisition of Mithril Medicine; the disclosed research remains predominantly preclinical.
👉 Keep the conversation going! Subscribe to our weekly newsletter for more insights, delivered straight to your inbox.